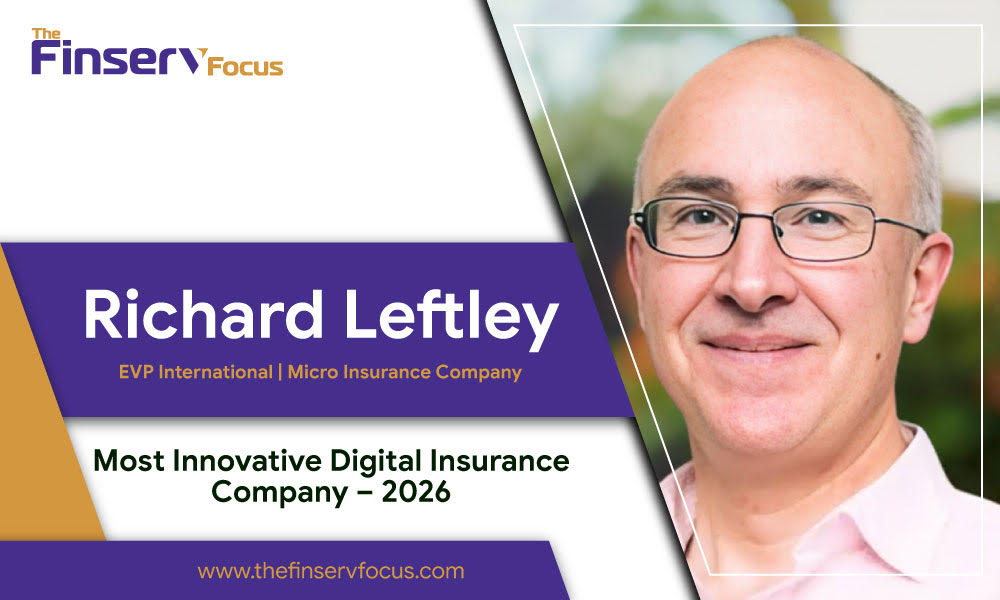
Technology is transforming the insurance industry by creating new ways for companies to reach customers, simplify processes, and deliver affordable financial protection. Artificial Intelligence, smartphones, mobile payments, and digital platforms are opening new opportunities, particularly in emerging markets where access to traditional insurance remains limited. Micro Insurance Company (MIC) has embraced these developments to expand insurance access and improve communication with underserved communities.
MIC was formed following the merger of several businesses, including MicroEnsure, which was founded by Richard Leftley. With extensive experience in microinsurance and emerging markets, Richard Leftley, EVP International at Micro Insurance Company, has played an important role in the company’s development and digital transformation.
Expanding Insurance Access in Emerging Markets
Micro Insurance Company primarily operates in emerging markets, including sub-Saharan Africa and Southeast Asia. These regions contain large populations that face significant financial risks while having comparatively limited access to insurance protection.
MIC focuses on developing innovative insurance solutions designed for mass-market customers. Its approach combines technology, partnerships, and simplified insurance products to make coverage more accessible to low- and middle-income communities.
Over the years, the company has witnessed major changes in digital technology. Markets have moved from feature phones to smartphones, while mobile money has evolved from airtime-based transactions to mobile wallets and in-app payments. MIC has leveraged these developments to distribute insurance products through communication providers and other strategic partners.
Building a Strong Partnership Network
Partnerships are an important component of Micro Insurance Company’s business model. The company collaborates with telecom operators, banks, microfinance institutions, and established insurance providers to extend its reach.
Its telecom relationships have included organizations such as Airtel, Telenor, Grameenphone, TNM, and Easypaisa. Through these networks, insurance products can reach customers through communication channels that they already use.
MIC has also worked with insurance companies including AXA, Shriram Life Insurance, Enterprise Group, Sanlam, Cornerstone, Jubilee Insurance, UT Life Insurance, and Old Mutual.
The company has developed relationships with banking and microfinance organizations as well, including Barclays, Opportunity International, FINCA, Advans, and Khushhali Microfinance Bank. These partnerships provide valuable industry expertise and distribution capabilities while supporting MIC’s goal of reaching more families with affordable insurance.
Richard Leftley’s Microinsurance Journey
Richard Leftley has been associated with the microinsurance sector since 2002, when he began working with Opportunity International, a leading microfinance organization, as a reinsurance broker.
During his time there, he helped introduce insurance products within the Opportunity Network. This work contributed to the development of what would become Micro Insurance Company.
His experience also includes involvement with the ILO Micro Insurance Innovation Fund, a $35 million initiative supported by the Gates Foundation. He has served on the Microinsurance Network Board and continues to contribute his experience through nonprofit and industry-related organizations.
This combination of insurance, technology, and emerging-market experience has supported MIC’s expansion. Under his leadership and with its wider team, the company grew from serving a relatively small customer base to reaching millions of people across countries in Africa and Asia.
Responding to the COVID-19 Crisis
The COVID-19 pandemic created significant challenges for the insurance industry and the communities MIC serves. Restrictions and reduced economic activity affected the livelihoods of many low-income customers, while demand for affordable health, life, and hospital-related protection increased.
MIC’s existing products included pandemic-related coverage in some markets, providing an important foundation during the crisis. The company also introduced specific COVID-19 insurance solutions designed to provide financial support related to hospitalization and fatalities.
In some markets, MIC supported small businesses with insurance protection for commercial assets as they resumed operations. It also worked with mobile partners to make health and life insurance available to customers, demonstrating how digital distribution could support insurance access during a period of disruption.
Technology and Communication at the Core
Effective communication is essential for a global insurance organization operating across multiple countries and time zones. MIC has adopted digital collaboration tools to help employees communicate and work together effectively.
The company’s use of platforms such as Slack supports internal communication and collaboration, particularly in remote-working environments. It has also utilized digital tools to simplify insurance claims and customer interactions.
MIC’s NoQuibblz application was developed to accelerate claims processes, while messaging platforms such as WhatsApp have provided additional channels for customer communication and document sharing.
Artificial Intelligence and other emerging technologies also represent opportunities for MIC to improve how it acquires, retains, and serves customers. By combining technology with insurance expertise, the company aims to make communication more efficient and insurance services more accessible.
The Future of Digital Microinsurance
The evolution from traditional insurance distribution toward digital insurance represents an important development for emerging markets. Micro Insurance Company has focused on this transition by combining technology, partnerships, and customer-focused insurance solutions.
Its long-term vision includes creating, selling, and servicing insurance products digitally across multiple markets. As smartphone adoption, mobile payments, and digital communication continue to develop, these technologies can create additional opportunities to expand insurance access.
Micro Insurance Company’s journey demonstrates how technology and strategic partnerships can help address the insurance needs of underserved communities. By continuing to invest in digital capabilities, communication, and innovative insurance solutions, MIC is working toward a more accessible and connected insurance ecosystem across emerging markets.